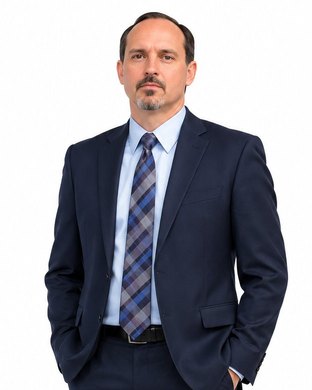
“This is your case. I’ll guide you and give you my honest advice, but every decision is yours. We’re a team, and I work for you.”
How he practices
Justin litigates his own injury cases. Clients are not handed off to a junior associate, and they can reach their attorney directly when something changes in their treatment, their work or their claim.
Most of a no-fault case is paperwork that has to be right: the application, wage proof, care and household logs, the medical record. When an insurer stops paying, the dispute usually turns on that record. The firm’s work starts with building it, and goes to court when the record supports a claim the insurer won’t pay.
In his words
How did you come to focus on injury and no-fault law?
I have practiced law in Michigan since 2007. I started out suing auto manufacturers and mortgage lenders, and that work taught me what still drives my practice: whether it’s a lender, a carmaker or an insurance company, it’s an ordinary person up against a multibillion-dollar corporation that would rather steamroll them than pay what it owes.
I never set out to switch to no-fault. I took on a crash case, took it to trial, and loved it. That client sent me a friend who had been in an accident, and that friend sent another. Almost all of my injury practice has grown that way, by word of mouth. These cases change people’s lives, and that is why I do them.
Whose case is it?
I tell every client who walks in the same thing: this is your case. Be proactive about your care and stay involved in your claim. If you’re unhappy with your doctor or therapist, go to someone else. And if you’re ever unhappy with me, fire me.
I’ll guide you and give you my honest advice, but every decision is yours to make. We’re a team, and I work for you.
Who actually works on my case?
I do. I’m personally involved in every part of every case. Someone on my staff may take your first call and gather the basic facts, but I meet with every client myself, and every client has my personal cell phone number.
What surprises people most on the first call?
Most people expect a lawyer to be expensive. They’re surprised to learn they pay no attorney fee and no costs unless I recover money for them.
They’re also relieved to hear that I will never push them into a settlement. Whether to settle or go to trial is their decision. Everyone has the right to their day in court, and to a lawyer who knows their case well enough to give them the best chance at a good result.
What kinds of cases do you take?
Many of mine are the hard ones: soft-tissue injuries the insurer insists can’t meet Michigan’s injury threshold, policies the insurer is trying to rescind, and disputes over whether coverage exists at all. Those are the cases where an insurer is counting on the injured person to give up. I take them, and I take them to court when I have to.
What are the denials you see most?
Delay. Many claims are never denied outright. The insurer stops paying and says it is “investigating,” and those investigations can drag on for years. It’s the oldest playbook in the business: delay, deny, defend. When I see it, I don’t wait. I file suit, because justice delayed is justice denied.
“Non-cooperation.” Insurers demand things the policy doesn’t require you to give them, then deny the claim when you don’t hand them over. Knowing exactly what you owe the insurer under your policy, and what you don’t, is often the whole case.
Coverage. Most often, the insurer says a premium wasn’t paid on time and the policy lapsed. The other common one is what insurers call a “material misrepresentation”: the policy lists the wrong address for where the car is kept, leaves off household members who drive, or doesn’t list people who regularly use the car.
On the claim against the other driver, the insurer usually says the injury doesn’t meet Michigan’s serious impairment threshold, or that its driver wasn’t at fault. Police reports contain a lot of mistakes, the officer often didn’t see the crash, and in Michigan the report itself generally can’t be used as evidence at trial. Being partly at fault doesn’t end your claim either: your damages are reduced by your share, and you lose pain and suffering only if you were more than 50% at fault. Your own no-fault benefits are paid regardless of fault.
When a denial comes in and the facts are on my client’s side, I don’t wait for the insurer to reconsider. I already know its position. I file suit and let a jury decide who is right.
What should I know about the insurer’s medical exam?
If your insurer is sending you to one of its exams, you should have a lawyer. Insurers call it an “independent medical exam.” I call it what it is, a defense medical exam, and that’s the only name I use in court. You see a doctor the insurer chose and pays, often for only a few minutes, and in my experience the report almost always ends with an opinion that your treatment should stop or that your injuries weren’t caused by the crash.
If the insurer really wanted to know how you’re doing, it would ask your own doctor, who has treated you all along. It doesn’t, because that wouldn’t give it a reason to cut off your benefits.
Be polite, on time and truthful, and don’t exaggerate. Michigan’s statute doesn’t say whether someone can come with you. When the insurer’s doctor objects, I ask the court for an order, and more and more often I ask that the exam be recorded so a jury can see exactly what happened in that room. Then I answer the report with medical experts of our own.
Will you tell me if I shouldn’t fight a denial?
Yes. My whole practice is built on telling clients the truth. I don’t sugarcoat, and you will always get my honest opinion. There are very few denials I would advise a client not to fight.
The exceptions are an unpaid premium, or a real material misrepresentation that the insurer can prove. In those cases I tell the client honestly that they will likely lose. It’s never a conversation I enjoy, but it’s better to be upfront than to promise something that can’t be achieved.
How long does a no-fault lawsuit take?
The more the insurer contests a case, the longer it takes. Insurers like to hold on to their money as long as they can, and Michigan has no bad-faith law to push them. Since the 2019 law change, they have even less reason to resolve claims quickly. Right now, the PIP cases I file are taking about 14 to 18 months to resolve after the lawsuit is filed.
How do you work with referring attorneys?
Many attorneys refer cases to me because they don’t practice personal injury law or aren’t licensed in Michigan. They refer the client, and I take it from there. I share a portion of the fee I collect with the referring attorney, with the client’s knowledge and agreement, as Michigan’s rules require.
It works the other way too. For mass tort litigation, or a client who lives in a state where I’m not licensed, I refer the case or bring in co-counsel who concentrates in that area.
Which courts do you practice in?
I’m licensed in Michigan and admitted to practice in federal court. I can appear in any court in Michigan, and with so many hearings now held by video, distance is rarely a barrier. When the law gives a choice of where to file, I choose the court that gives my client the best chance at a full recovery.
See case results from Justin’s files: what the insurer offered, what he did, and how each case ended.
Who he represents
- People hurt in crashes, for no-fault benefits and, when the injury meets Michigan’s threshold, claims against the at-fault driver.
- Families managing a claim for someone who can’t, including attendant care and survivors’ benefits.
- Medical providers with unpaid or disputed no-fault bills.
What clients have said
“Justin helped me settle a lengthy case I’ve been trying to wrap up for years.”
“Everyone at the Grove Law Firm was professional, knowledgeable and kind. I highly recommend this law firm.”
Before you hire any lawyer
You can confirm any Michigan lawyer’s license and discipline history in the State Bar of Michigan member directory. Ask who will handle the case day to day, how fees and costs work, and how you’ll hear about progress. Our checklist of questions to ask applies to us as much as anyone, and our fee page explains how contingency fees work.
Contact Justin
Call 313.733.1204; a person answers day or night. Or write to the office at 36700 Woodward Ave., Suite 107, Bloomfield Hills, MI 48304.